By Patricia A. Boyes, Principal Attorney, BoyesLegal, APC (San Jose, California) | Last reviewed: September 2026
Your will says your daughter should receive your investment account. But years ago, you named your son as the account’s transfer-on-death beneficiary and never changed it. Who gets the money?
Most likely, your son.
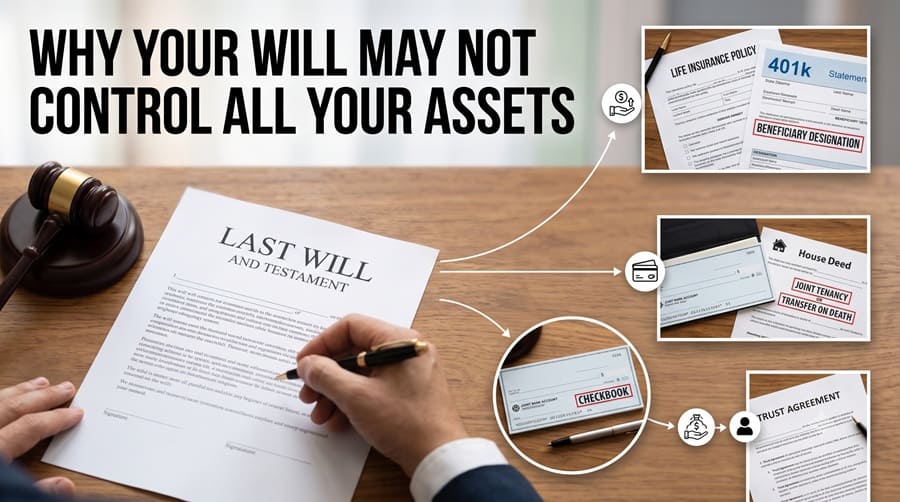
Many people assume a will is the final word on who inherits. In California, as in every state, a will controls only the property that ends up in your probate estate. Beneficiary designations, trusts, and some forms of co-ownership operate on their own, and when they point in different directions from the will, they usually win.
Where Each Asset Actually Goes
| Asset | What decides who receives it | Does the will control it? |
| Life insurance | The beneficiary designation with the insurer | No |
| 401(k), IRA, pension | The plan’s beneficiary form (and federal spousal rules for many employer plans) | No |
| Payable-on-death bank account | The named POD payee | No |
| Transfer-on-death brokerage account | The TOD beneficiary on file | No |
| Home held in joint tenancy | The surviving joint tenant | No |
| Home with a transfer on death deed | The deed’s named beneficiary | No |
| Assets titled in a living trust | The trust document | No |
| Individually owned property with none of the above | The will (or intestacy if there is no will) | Yes |
What Actually Passes Through Your Will?
A will governs your probate estate: property you own individually that has no beneficiary designation, isn’t held in a trust, and doesn’t pass automatically to a co-owner. Your will tells the executor how to distribute those assets. It can also nominate guardians for minor children and name the person who will settle your affairs.
California law expressly recognizes the other routes. Under Probate Code § 5000, provisions in insurance policies, account agreements, and similar written instruments that direct where property goes at death are valid transfers that operate outside the will. In practice, for many families, the will ends up controlling only a car, some household goods, and whatever accounts were never set up with a beneficiary.
Beneficiary Forms Usually Win
Life insurance proceeds are paid directly to the named beneficiary. Funds in a payable-on-death bank account belong to the POD payee at death under Probate Code § 5302. Securities registered in transfer-on-death form pass to the named beneficiary under California’s version of the Uniform TOD Security Registration Act (§ 5501 and following). Retirement accounts follow the plan’s beneficiary form.
Changing your will doesn’t change any of those. That’s how an old form creates an unintended result: you named one child when you opened your first retirement account and later had another; your primary beneficiary died and you never named a contingent beneficiary, so the account defaults to your estate; or you remarried and never updated anything.
The divorce trap
California does some of the cleanup automatically. After a marriage is dissolved or annulled, many nonprobate transfers to the former spouse fail under Probate Code § 5600. But that rule has exceptions, and it doesn’t reach employer retirement plans governed by federal ERISA law. In Egelhoff v. Egelhoff (2001), the U.S. Supreme Court held that the plan administrator must pay the beneficiary named in the plan documents, even a former spouse, regardless of state revocation statutes. The only reliable fix is updating the form itself.
California’s Community Property Adds Another Layer
California is a community property state, and that limits what a married person can give away. Under Probate Code § 100, each spouse owns half of the community property, so a will can dispose of only the testator’s half. A beneficiary designation naming someone other than the spouse on an account funded with community earnings can also be challenged by the surviving spouse to the extent of their community interest unless the spouse consented in writing (Probate Code § 5020 and following).
Federal law goes further for many employer plans. Under 29 U.S.C. § 1055, a married participant in a pension or 401(k) plan subject to these rules generally can’t name anyone other than their spouse as beneficiary without the spouse’s notarized or plan-witnessed written consent. A form that skips that step may not work the way it looks.
How Title Decides What Happens to Property
Two names on a deed don’t say enough on their own. The form of ownership matters:
- Joint tenancy (Civil Code § 683) carries a right of survivorship. When one joint tenant dies, the property belongs to the survivor, whatever either will says.
- Community property with right of survivorship (Civil Code § 682.1) lets married couples and registered domestic partners combine community property treatment with automatic survivorship.
- Tenancy in common has no survivorship. Each owner’s share passes under their own will or trust, which is how unrelated co-owners and siblings can end up sharing property with a stranger’s heirs.
- A revocable transfer on death deed (Probate Code § 5614 and following) lets a homeowner name a beneficiary who takes the home at death outside probate, with no effect during the owner’s lifetime.
Bank and brokerage accounts work similarly: an account opened “jointly” for convenience, so a child could help pay bills, may legally pass to that child alone, cutting out siblings the will treats equally.
A Dispute Over How a Home Was Owned
Title questions don’t only come up at death. Among the matters listed on BoyesLegal’s case results page is a dispute over respective ownership interests in a residential property, in which the other side claimed an ownership share based on a domestic partnership. The firm represented the defendant, and the case was resolved through mediation.
Cases like that show why the paperwork behind a home deserves as much attention as the will. When the deed, the relationship, and each person’s understanding of who owns what don’t line up, the dispute often lands on the family after a death, when the person who could have explained it is gone. Families in that position can find a practical starting point in this guide to the steps after a loved one’s passing.
Every case is different, and prior results do not guarantee a similar outcome.
A Trust Controls Only What’s Actually in It
Property properly transferred into a living trust passes under the trust’s terms, not the will. Problems start when the paperwork falls behind: a house refinanced out of the trust and never deeded back, a brokerage account opened years later in the owner’s own name, or a trust and will written at different times with instructions that no longer match.
A pour-over will (Probate Code § 6300) can direct leftover assets into the trust, but it doesn’t keep them out of probate. Those assets still go through a court process first unless a shortcut applies; for deaths on or after April 1, 2025, personal property up to $208,850 can often be collected by affidavit (§ 13100) and a primary residence worth up to $750,000 may pass by a simplified petition (§ 13151). For a sense of where do-it-yourself plans most often leave these gaps, see this look at the pros and cons of DIY estate planning.
Do an Asset-by-Asset Check
The most useful way to review an estate plan is to stop reading it as a stack of documents and start with the assets themselves. For each one, answer a single question: if I died today, where would this actually go?
- Your home. Pull the current deed. Is it in the trust, in joint tenancy, or in your name alone?
- Retirement accounts. Log in or call the plan. Who is the primary beneficiary, and is there a contingent?
- Life insurance. Request a beneficiary confirmation from each insurer, including employer group policies.
- Bank and brokerage accounts. Check for POD or TOD designations and joint owners.
- Compare. Put the answers next to what your will and trust say, and note every mismatch.
An estate planning attorney can help identify where ownership documents, beneficiary designations, a trust, and a will no longer point toward the same goal. Natural times to do this are after a marriage, divorce, birth, or death in the family, after buying or refinancing a home, and after opening new accounts.
Frequently Asked Questions
Does a will override a beneficiary designation in California?
No. Life insurance, retirement accounts, and POD or TOD accounts pass to the named beneficiary regardless of the will. The only way to change them is to update the designation with the institution.
What happens if the beneficiary on my account has died?
If there is no living contingent beneficiary, the account usually defaults under the account terms, often to your estate, where it may be subject to probate and pass under your will.
Does joint tenancy override a will?
Yes. Property held in joint tenancy passes to the surviving joint tenant automatically. Tenancy in common does not have that effect.
Can I leave all our community property to my children in my will?
Only your half. In California, the surviving spouse already owns the other half of community property.
Does divorce remove my ex-spouse as beneficiary automatically?
For many California assets, yes, but not for employer retirement plans governed by ERISA, where the form on file controls. Update every designation after a divorce.
Disclaimer
This article provides general information about California estate planning and is not legal advice. Reading it does not create an attorney-client relationship. How a particular asset transfers depends on its documents, title, and applicable law, which can change. For advice about your situation, consult a licensed California attorney.