By Aaron T. Hicks, Founding Partner, Hicks Law Firm, PC, Orange, California · Updated November 2026
When three or more cars collide, fault rarely lands on one driver. It gets divided. California’s comparative fault rules were built for this situation: fault is assigned in percentages across everyone involved, and an injured person’s recovery is reduced only by their own share. Even a driver who bears some blame may still recover meaningful compensation.
The hard part is figuring out how that fault gets divided and which driver, or which insurer, actually pays. In California, that second question has a twist many people don’t expect, because the answer depends on the type of damages involved.
Quick Answer
Each at-fault driver pays a share based on their percentage of fault. Your recovery is reduced by your own percentage, with no cutoff. Medical bills, lost wages and other economic losses can be collected in full from any at-fault driver who is jointly responsible. Pain and suffering is different: each driver owes only their own percentage of it. If you were driving without insurance, you generally cannot recover pain and suffering at all.
How California’s Pure Comparative Fault Rule Works
California follows pure comparative fault. The state Supreme Court adopted the rule in Li v. Yellow Cab Co. (1975), applying the general negligence principle in Civil Code section 1714. Under it, fault for a crash can be divided among all parties as percentages, and each person’s damages are reduced only by their own percentage.
Many states bar recovery once a driver is more than 50 percent at fault. California has no such cutoff. A driver who is 90 percent at fault can still recover 10 percent of their damages.
In a multi-car crash, fault might be divided this way: Driver A, 60 percent; Driver B, 30 percent; Driver C, 10 percent. Each driver’s share then shapes both what they owe and what they can recover.
Economic vs. Non-Economic Damages: The Proposition 51 Rule
This is the piece many pileup articles leave out. In 1986, California voters passed Proposition 51, now Civil Code section 1431.2. It splits damages into two categories:
- Economic damages, such as medical bills, lost income and car repairs, remain “joint and several.” You can collect the full amount from any at-fault driver, who can then seek reimbursement from the others.
- Non-economic damages, such as pain, suffering and emotional distress, are “several” only. Each at-fault driver pays just their own percentage.
That difference matters most when one driver has little or no insurance. You can still recover your economic losses from a driver who does have coverage, but the uninsured driver’s share of your pain and suffering may be uncollectible.
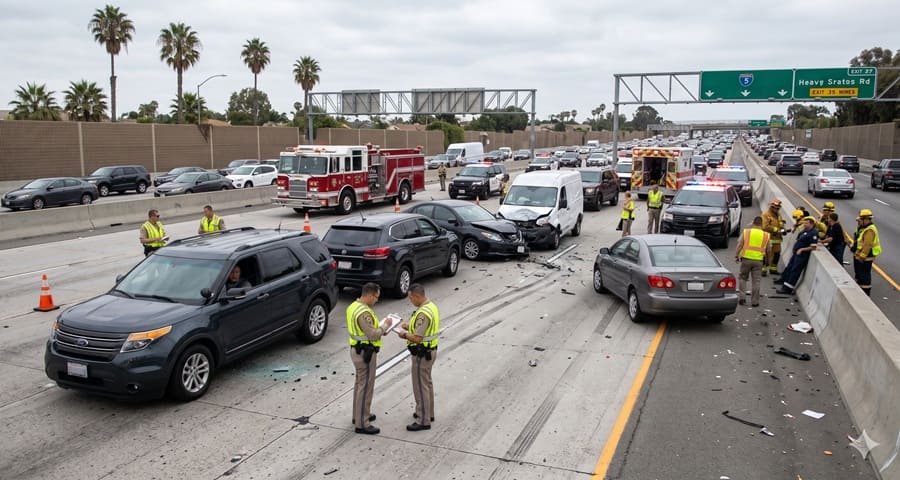
A Worked Example: A Three-Car Pileup on the 405
Suppose you’re in a three-car crash on the 405 near Irvine. A jury finds your total damages are $200,000: $80,000 in economic losses and $120,000 in non-economic losses. Fault is divided this way: the rear driver, 70 percent; you, 20 percent; a third driver, 10 percent.
| Item | Calculation | Amount |
| Total damages | $80,000 economic + $120,000 non-economic | $200,000 |
| Your 20% reduction | 20% of $200,000 | −$40,000 |
| Economic damages recoverable | 80% of $80,000, collectible from either at-fault driver | $64,000 |
| Non-economic from rear driver | 70% of $120,000 | $84,000 |
| Non-economic from third driver | 10% of $120,000 | $12,000 |
| Total recovery | $160,000 |
If the third driver turns out to be uninsured and has no assets, the full $64,000 in economic damages can still come from the rear driver, but the $12,000 non-economic share may be lost. Proving both your total damages and your limited share of fault is where most of the work in a pileup claim lies.
The Chain-Reaction Problem
Most pileups unfold in a chain. One collision sets off the next, and sorting out which impact caused which injury gets complicated fast.
- Was the first driver who braked suddenly negligent, or reacting to a hazard?
- Was the car behind following too closely, in violation of Vehicle Code section 21703?
- Was a third driver going faster than conditions allowed under the basic speed law, especially in fog, rain or heavy traffic?
Each answer changes the fault percentages. Accident reconstruction experts often analyze speed, braking distance and the sequence of impacts. Medical records matter too, since a person hit twice may need a doctor to explain which collision caused which injury.
Evidence That Establishes Fault
A police report is where most cases start, but rarely where they end. The evidence that tends to matter most includes:
- the California Highway Patrol or local police report and any citations
- statements from other drivers, passengers and bystanders
- traffic camera and dashcam footage, which may be overwritten within days
- skid marks, vehicle positions, debris and damage patterns
- event data recorders that log speed and braking in the seconds before impact
- phone records, when distraction may be involved
The more vehicles involved, the more investigations run in parallel, and the findings don’t always agree. For steps to take in the first days after a crash, see this guide on what to do after a car accident that’s not your fault.
When Several Insurers Are Involved
A pileup means dealing with several insurance companies at once. Each one represents its own policyholder and has a reason to push fault onto someone else, including you.
| Scenario | Who you deal with | Key challenge |
| One driver caused the crash | That driver’s insurer | Proving fault and total damages |
| Two drivers share fault | Two separate insurers | Disputed fault percentages |
| Three or more drivers | Several insurers at once | Delays and blame-shifting |
| At-fault driver is underinsured | Their insurer, then your UIM carrier | Exhausting their limits before UIM pays |
Insurers may argue among themselves for months over who owes what, and after paying, one insurer may pursue another for reimbursement, a process called subrogation. Meanwhile, the injured person’s bills keep arriving. California’s minimum liability coverage is $30,000 per person and $60,000 per accident, which can run out quickly when several people are hurt. Underinsured motorist coverage under Insurance Code section 11580.2 can help, but it generally applies only after the at-fault driver’s limits are paid, and it is reduced by what that driver’s insurer paid. This piece on common insurance tactics that leave crash victims in debt covers some of the pressure points.
Rules That Can Limit or Bar Recovery
- Uninsured drivers: Under Civil Code section 3333.4 (Proposition 213), a driver who was uninsured at the time of the crash generally cannot recover non-economic damages from other drivers, even if someone else was mostly at fault.
- Deadline to sue: Most personal injury lawsuits must be filed within two years under Code of Civil Procedure section 335.1.
- Government vehicles or roads: If a city bus, Caltrans or another public agency may share fault, a written claim generally must be filed within six months under Government Code section 911.2.
Where Fault Allocation Shows Up in Real Cases
The firm’s published results include a $655,000 recovery in a rear-end collision case and a $210,000 recovery in a collision between two semi-trucks. The published summaries list amounts and case types rather than case facts. Rear-end and commercial-vehicle crashes are common starting points for chain-reaction claims, though, and in cases like these, how fault is divided between drivers, and which insurers sit behind them, often shapes the final number as much as the injuries do.
Past results do not guarantee a similar outcome. Every case depends on its own facts, the available insurance and the evidence of fault and damages.
What a Lawyer Does in a Pileup Case
In a two-car crash, fault is often straightforward. In a pileup, it rarely is. Orange County personal injury attorneys who handle multi-vehicle cases typically start by preserving evidence before it disappears, identifying every driver and insurance policy involved, and bringing in reconstruction experts where the sequence of impacts is disputed. They also track which damages are joint and several and which are not, so a recovery isn’t lost to an uninsured driver’s share.
Evidence fades and witnesses forget. Starting early, before insurers have locked in their versions of events, usually gives an injured person more options.
Disclaimer
This article provides general information about California law and is not legal advice. Reading it does not create an attorney-client relationship. Insurance requirements, damages rules and deadlines can change, and the outcome of any claim depends on its specific facts. For advice about your situation, consult a lawyer licensed in California.